Travel Insurance Decisions
Do You Need Travel Insurance If Your Flight or Hotel Is Refundable?
A refundable flight or hotel can reduce one important risk: losing the money tied to that reservation if your plans change within the provider’s rules. Travel insurance addresses a different set of risks — and may or may not add enough value to justify the cost.
The decision: After accounting for everything you can already refund, credit, or recover, are the remaining trip costs and travel risks large enough that you would rather transfer some of that risk to an insurance policy than carry it yourself?
This guide separates refundable booking rules from broader travel-insurance protection so you can decide based on the risks that actually remain.
On this page
- Quick Answer
- Decision in 30 Seconds
- Refundable Is Not the Same as Insured
- What Refundability Protects
- What It Does Not Protect
- The Medical Risk Question
- How Refundable Is the Whole Trip?
- Credit-Card Travel Protection
- When Insurance May Add Less Value
- When It May Add More Value
- The Trip Exposure Test
- Fine Print
- TFP Recommendation
- Before You Go
- FAQ
Quick Answer
Do you still need travel insurance if your bookings are refundable?
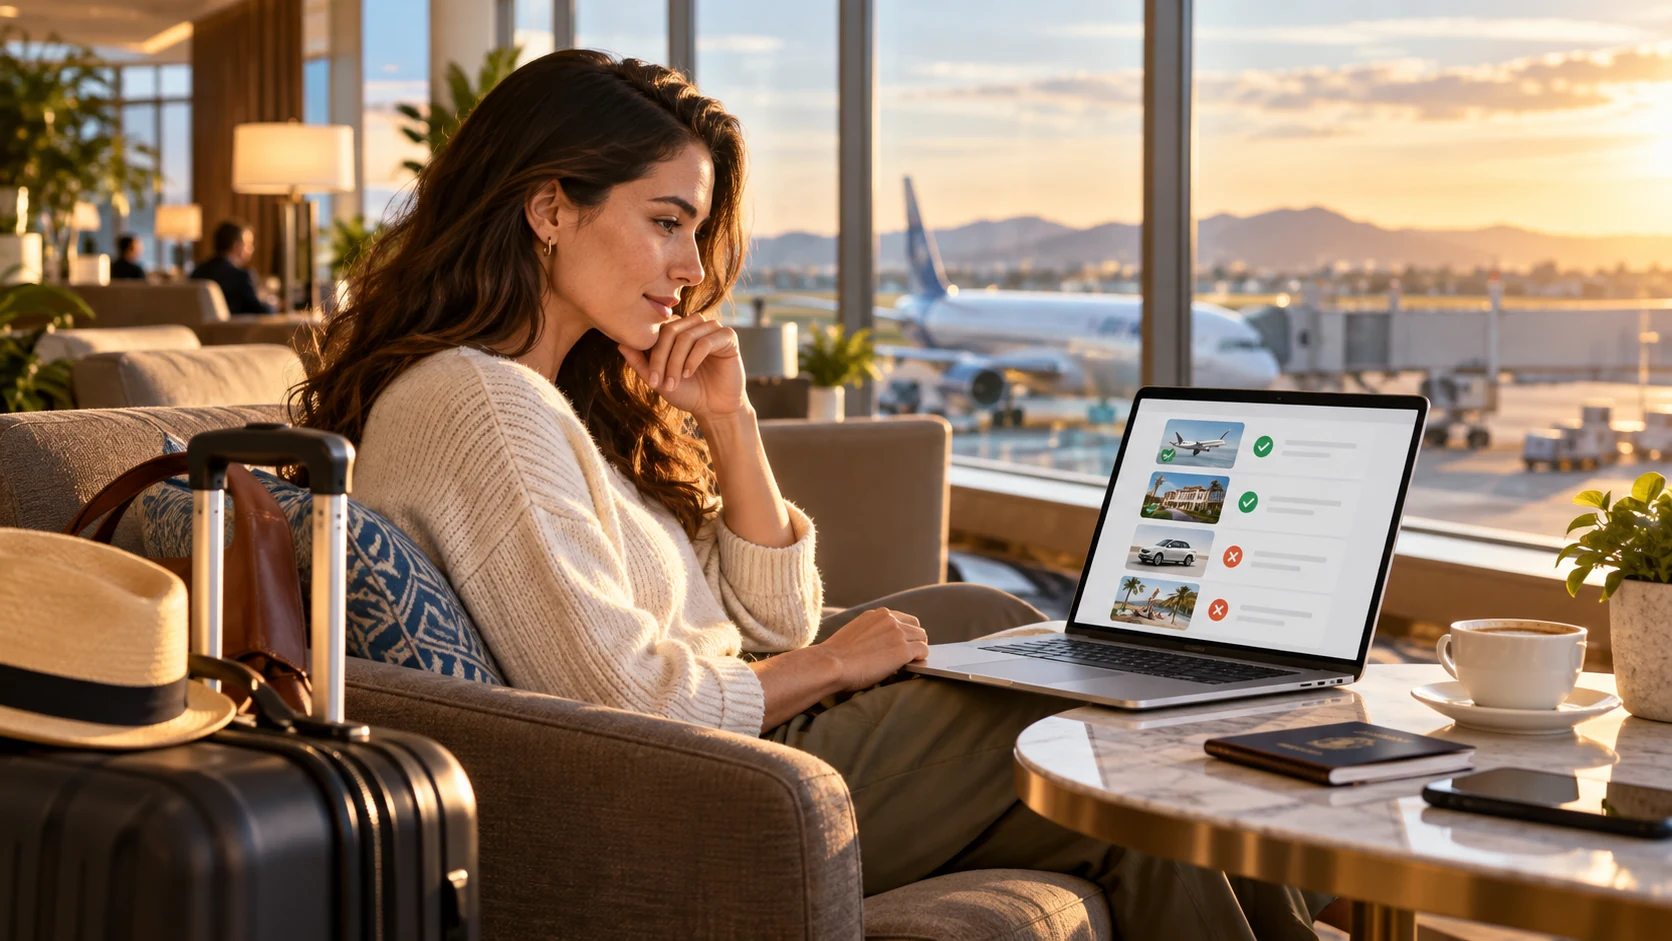
Not automatically. If most of the trip can be refunded or changed without a meaningful penalty and you can comfortably absorb the remaining risks, a separate policy may add limited value.
But refundability mostly addresses booking value. It does not by itself address medical expenses, an interrupted trip, delay costs, baggage problems, or non-refundable pieces elsewhere in the itinerary. Those remaining exposures are what should drive the insurance decision.
Decision in 30 Seconds
Look at the whole trip — not just the refundable booking.
Start with what you could actually lose. Then separate cancellation exposure from the risks that can arise after the trip begins.
| Your situation | What remains exposed? | How to think about insurance |
|---|---|---|
| Simple domestic trip, low cost, mostly refundable | Usually a relatively small amount of unrecoverable trip cost. | A separate policy may add limited value if your existing health coverage and other protections leave no gap that concerns you. |
| Refundable flight + non-refundable hotel, tour, or cruise | The airfare may be protected, but other prepaid costs can still be at risk. | Insurance may still be worth considering for the non-refundable pieces and other covered losses. |
| Mostly refundable international trip | Trip costs may be flexible, but medical treatment or emergency transportation may still be an important exposure. | Check how your existing health coverage works at the destination before deciding that refundability makes insurance unnecessary. |
| Expensive multi-part trip | Flights, hotels, tours, cruises, transfers, and activities may all have different rules. | Evaluate total exposure rather than assuming one refundable component protects the trip. |
The Core Distinction
A refundable booking is not the same as being insured.
Refundable is a booking term, not a risk profile. It tells you what may happen to the value of a specific reservation if you cancel or change it under the provider’s rules.
Travel insurance answers a different question: “If a covered travel problem happens, which losses does the policy protect — and under what conditions?”
Refundable booking
Protects the reservation value, subject to the airline, hotel, cruise line, tour operator, or other provider’s cancellation terms and deadlines.
Travel insurance
May protect against covered losses such as trip cancellation or interruption, medical expenses, delays, baggage problems, or other risks defined by the policy.
What Refundability Does
What does a refundable flight or hotel actually protect?
Usually, it protects some or all of the value of that specific reservation if you cancel within the provider’s rules. The exact outcome depends on the rate or fare terms.
Refundable flight
You may be able to cancel and recover the airfare according to the fare rules. That does not automatically refund your hotel, tour, rental car, cruise, or other bookings.
Refundable hotel
You may be able to cancel without penalty until a specified deadline. Once the deadline passes, different terms may apply.
Flexible reservation
Some bookings allow changes or cancellation but return value as a credit rather than cash. Read the actual terms rather than relying only on labels such as “flexible.”
Fine-print check
“Refundable,” “flexible,” “free cancellation,” and “changeable” do not always mean the same thing. Verify the deadline, refund method, penalties, and whether any portion of the booking remains non-refundable.
What Refundability Does Not Do
What risks can remain even when the booking itself is refundable?
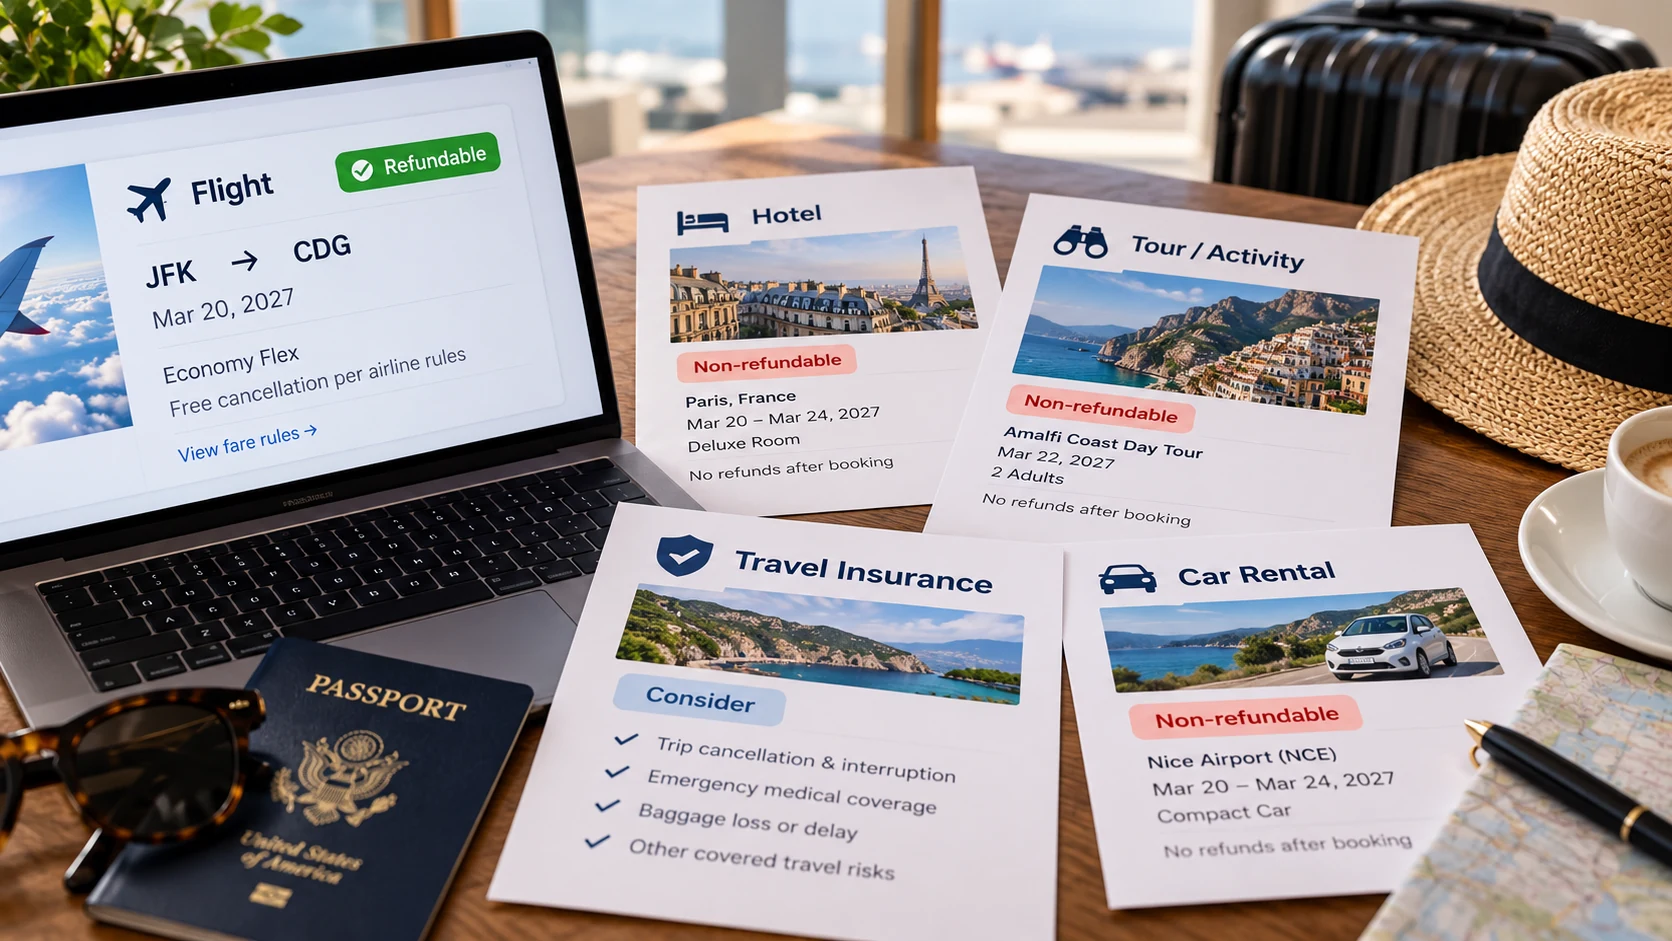
Refundability can reduce the loss tied to one reservation. It does not automatically address the other expenses and disruptions that can occur before or during the trip.
Other non-refundable trip costs
A refundable flight does not protect a prepaid cruise, tour, villa, event ticket, transfer, or another booking with stricter terms.
Trip interruption
You may have to return home early, buy new transportation, or abandon unused parts of the trip even though the original flight was refundable.
Travel delays
Meals, hotels, local transportation, and other delay-related costs can arise without affecting whether your original reservation was refundable.
Baggage problems
Lost, delayed, stolen, or damaged baggage is a separate risk from the refundability of your flight or hotel.
Medical emergencies
A refundable airline ticket does nothing by itself to pay for medical treatment or emergency transportation while you are traveling.
The Often-Overlooked Risk
Medical exposure can matter more than the cost of the flight.
Travelers often focus on whether they could lose the airfare because that number is easy to see before the trip. On some itineraries — especially international ones — the more important unanswered question may be how unexpected medical care or emergency transportation would be handled.
A fully refundable $1,000 ticket protects the ticket value under its rules. It tells you nothing about what your health plan, credit card, or a travel-insurance policy would pay if you needed treatment while traveling.
Ask a different question.
Instead of only asking, “How much money could I lose if I cancel?” also ask, “What could become expensive after the trip has already started — and what protection would I have then?”
Whole-Trip Flexibility
How refundable is the entire trip?
The answer can be very different depending on whether one component is refundable or almost everything is.
Mostly refundable trip
Your flight, hotel, and major prepaid reservations can all be canceled with little or no penalty. Cancellation coverage may add less value, although other insurance benefits can still matter.
One refundable component
Your airfare may be refundable while hotels, tours, cruises, villas, or activities are not. The refundable flight may represent only a small part of the total exposure.
Do not let the most visible reservation determine the decision. Add up the costs that would actually remain at risk after every available refund, cancellation right, credit, or other recovery.
Check Existing Protection First
What if your credit card already includes travel protection?
Some credit cards include travel-related benefits when eligible trip costs are charged to the card. Those benefits can overlap with parts of a separate travel-insurance policy, but a benefits package is not automatically a substitute for one.
Before buying additional coverage, review the card’s benefit guide for covered reasons, limits, eligible travelers, payment requirements, trip interruption, delay, baggage, rental-car protection, and whether medical or emergency-transportation benefits are included at all.
Avoid comparing labels.
“Trip cancellation,” “travel delay,” or “baggage protection” can appear on both a credit-card benefit and a travel-insurance policy while having very different limits, exclusions, triggers, and documentation requirements.
When It May Add Less Value
When can skipping separate travel insurance be reasonable?
There is no rule that every trip needs a separate policy. Insurance may add less value when the losses you cannot otherwise recover are limited and the remaining risks would not create a financial problem for you.
Most major trip costs are refundable
You would recover most of the prepaid money even if you had to cancel.
The trip is relatively inexpensive
The amount you could lose is small enough that paying an insurance premium may not be compelling.
You already have meaningful protection
Credit-card benefits, existing medical coverage, or other protections may already address some of your main concerns.
You can comfortably self-insure
You are financially comfortable absorbing the costs that remain if the trip goes wrong.
When It May Add More Value
When can travel insurance still be worth considering?
Meaningful non-refundable costs remain
Other trip components could still represent a substantial loss even though the airfare or hotel is refundable.
Your existing medical protection leaves a gap
If your health coverage is limited at the destination, medical and emergency-transportation benefits may matter more than cancellation protection.
The trip would be expensive to interrupt
Returning home early or replacing transportation could create costs far beyond the original refundable reservation.
The trip has many moving parts
Flights, cruises, tours, hotels, transfers, events, and other components can each have different cancellation and refund rules.
The Trip Exposure Test
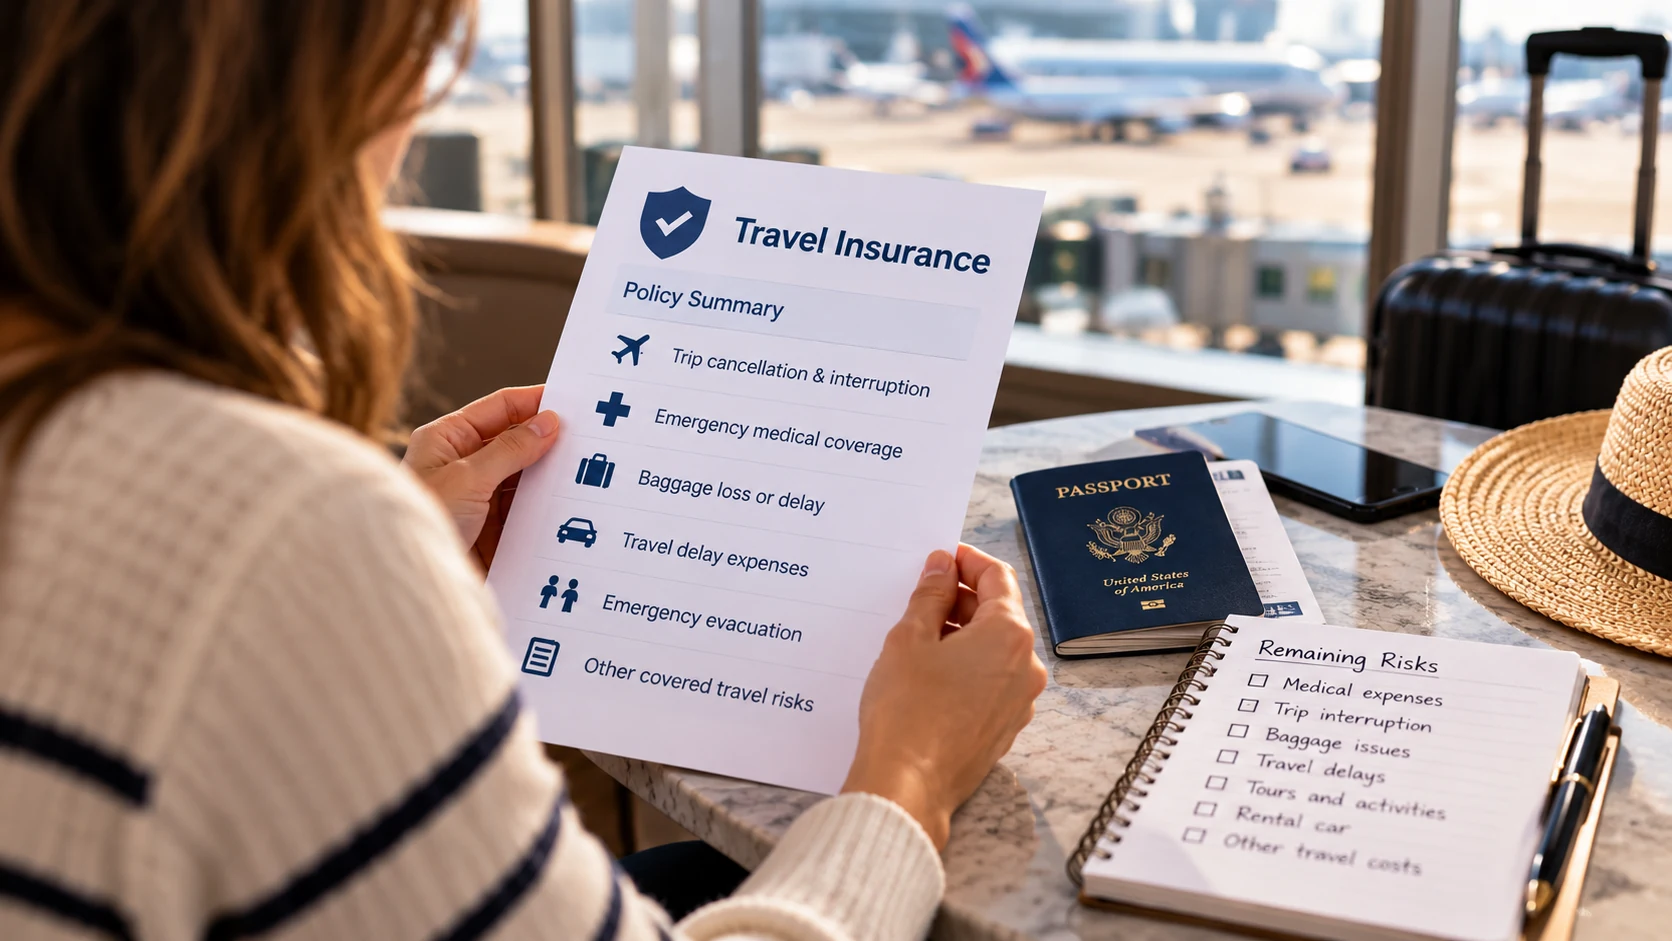
Use this test before paying for a policy — or deciding to skip one.
1. What money could I still lose?
Add up the trip components that would not come back to you if you had to cancel or interrupt the trip.
2. What risks remain beyond cancellation?
Think about medical treatment, evacuation, interruption, delays, baggage, and other travel problems relevant to your trip.
3. What protection do I already have?
Check provider refund rules, credit-card benefits, medical coverage, and any other protection before paying for overlapping benefits.
Then ask: Would the remaining loss matter?
If the remaining exposure would be an inconvenience you can comfortably absorb, carrying the risk yourself may be reasonable. If it could meaningfully disrupt your finances or the trip, compare the available protection more closely.
The Fine Print That Matters
Five things to verify before treating “refundable” as enough protection.
Refundable can still have a deadline.
A booking may be fully refundable only until a certain date or time. After that, a penalty or non-refundable period may begin.
A refund and a travel credit are not the same thing.
Some flexible bookings return value as a credit with restrictions or an expiration date rather than cash.
One refundable reservation does not make the trip refundable.
Every hotel, tour, cruise, transfer, activity, rental, and ticket may have its own cancellation rules.
Travel insurance covers specific risks, not every bad outcome.
Benefits depend on covered reasons, exclusions, limits, timing requirements, and the policy terms.
Existing benefits can change the value calculation.
Credit-card protections or other coverage may reduce the need for some benefits, but compare the actual terms rather than assuming they are equivalent.
My Take
I would not let the word “refundable” make the decision for me.
I would first remove every cost I know I could recover, then look at what is left: non-refundable reservations, medical exposure, interruption costs, delays, baggage, and any protection I already have through a credit card or health plan.
On a simple, inexpensive, mostly refundable trip, I may be comfortable carrying the remaining risk myself. On a complex or expensive trip, the refundable airfare may be one of the least important pieces of the decision.
TFP Recommendation
Base the decision on your remaining exposure — not on whether one booking says “refundable.”
The Recommendation
Calculate your remaining exposure before you compare policies.
If the costs and risks left after refunds and existing benefits are small enough that you would comfortably absorb them, a separate policy may not be necessary. If the remaining exposure is meaningful, compare coverage, exclusions, limits, and price against the specific risks you want to transfer.
Your Next Step
Choose the path that matches your trip.
Smarter travel, straight to your inbox
Booking choices, hidden costs, travel rules and useful fine print — explained clearly.
Before You Go
Make the rest of the trip easier to evaluate before departure.
These related guides cover claim documentation, flight-delay coverage, hotel payment flexibility, and the fine print that can matter if plans change later.
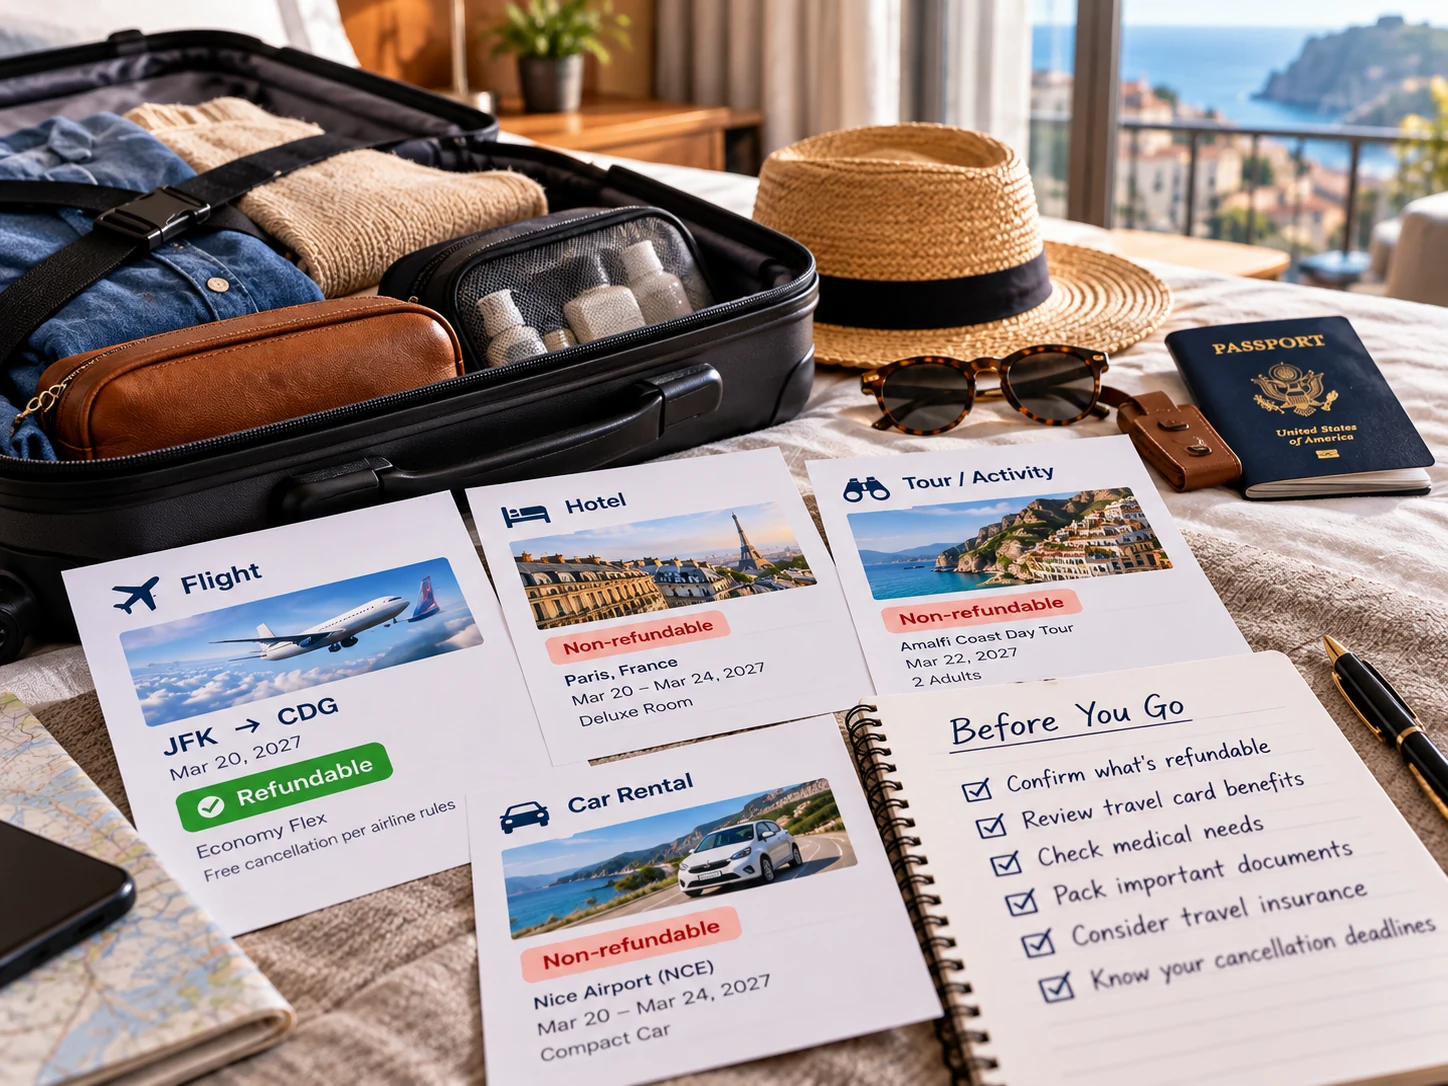
Travel Insurance Claim Proof
See what receipts, provider records, and proof of loss may need to show if you eventually file a claim.
Understand claim proof →Does Travel Insurance Cover Flight Delays?
Learn how delay coverage can differ from airline refunds, rebooking, and other carrier obligations.
Understand delay coverage →Why Travel Insurance Claims Get Denied
Understand how covered reasons, exclusions, timing, and documentation can affect a claim.
Understand claim denials →Pay Now vs Pay at Hotel
Compare prepaid hotel rates with more flexible payment and cancellation options before you book.
Compare hotel payment options →Frequently Asked Questions
Refundable bookings and travel insurance
Do I need travel insurance if my flight is refundable?
Not necessarily. A refundable flight reduces the money at risk in the airfare itself. Whether travel insurance still adds value depends on the rest of the trip and other risks such as medical expenses, interruption, delays, baggage, and non-refundable bookings.
Do I need travel insurance if my hotel is refundable?
A refundable hotel can reduce cancellation exposure for that reservation, but it does not protect other bookings or broader travel risks. Look at the trip as a whole before deciding.
Is travel insurance worth it if everything is refundable?
It may add less value for trip-cancellation protection when nearly all prepaid costs are recoverable. Other benefits — such as medical, evacuation, interruption, delay, or baggage coverage — may still matter depending on the trip and policy.
Does a refundable ticket cover medical emergencies?
No. Refundability relates to the booking’s cancellation rules. It does not by itself provide medical coverage while you are traveling.
Can credit-card travel insurance replace a separate policy?
Sometimes card benefits may cover some of the same risks, but the limits, covered reasons, eligible travelers, payment requirements, and medical benefits can differ significantly. Compare the actual benefit guide with the policy you are considering.
What should I check before buying travel insurance?
Identify what trip costs are non-refundable, what protection you already have, what medical or interruption risks remain, and whether you can comfortably absorb the remaining exposure yourself.
Does travel insurance pay if the airline or hotel already refunds me?
A refund can reduce or eliminate the loss tied to that specific expense. Whether anything else is payable depends on the policy, the covered event, and any other eligible losses. Keep records of refunds, credits, vouchers, and reimbursements so the remaining claim amount can be evaluated correctly.
Free Travel Guide
Avoid the travel mistakes that can cost you money, flexibility, or time.
Get 27 Travel Mistakes That Cost Travelers Thousands — a practical guide to booking mistakes, hidden costs, travel rules and decisions worth understanding before they become a problem.
- Spot booking details that are easy to overlook
- Understand where hidden costs can appear
- Recognize when a cheaper option comes with a tradeoff
- Make travel decisions with fewer surprises
You’ll also receive occasional practical guidance from Travel Fine Print on booking choices, hidden costs, travel rules and the fine print worth understanding. Unsubscribe anytime.